
Key Takeaways
- Clear, plan-neutral education about urgent care and ER costs supports smarter client healthcare decisions.
- Compliance-focused communication protects your practice and builds lasting trust with Medicare clients.
Did you know many Medicare clients could save significantly by understanding when to choose urgent care over the ER? Clear, compliant education makes a measurable difference. Here’s how you can empower Medicare beneficiaries to make informed, cost-effective choices while building trust—and protecting your practice.
What Are Urgent Care and ER Services?
Defining urgent care for Medicare clients
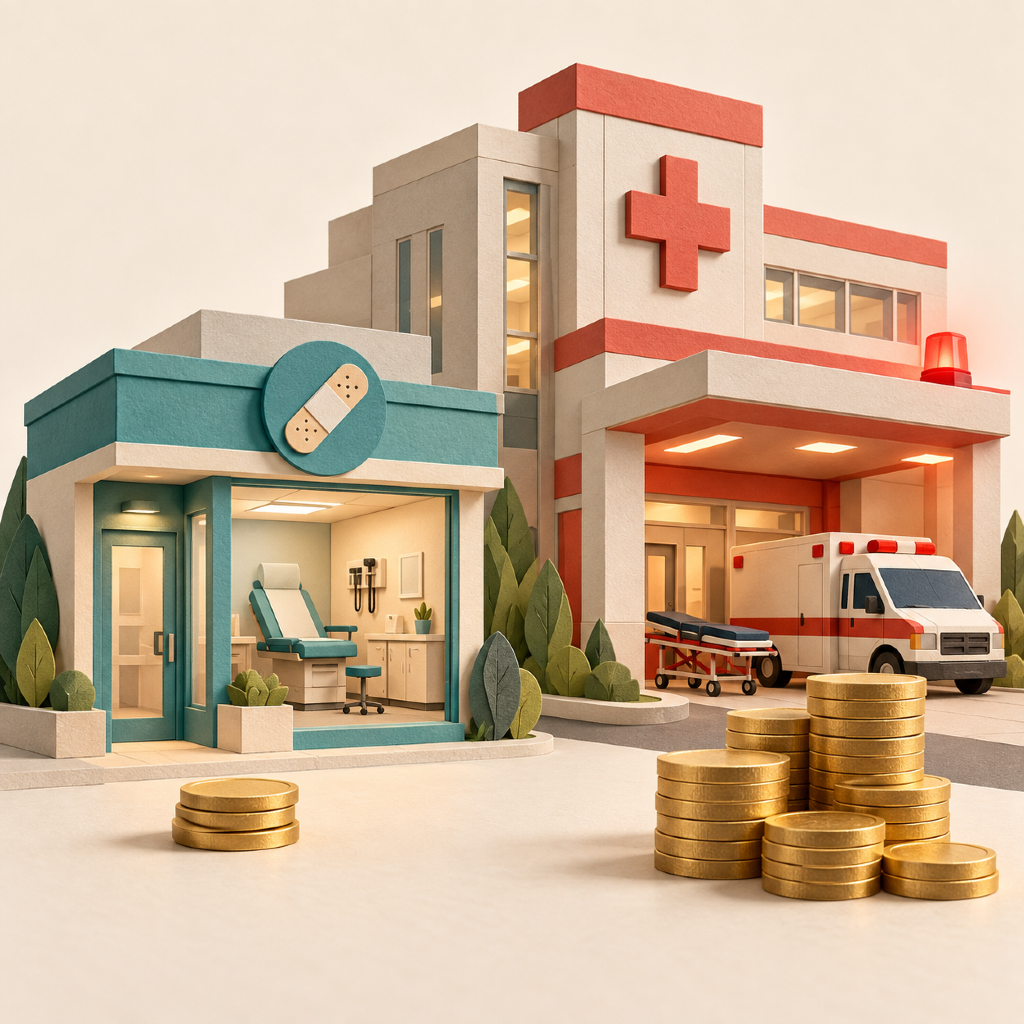
Urgent care centers fill a crucial gap between routine primary care and the higher acuity care provided by emergency rooms. For Medicare clients, urgent care is best positioned for conditions that require prompt attention but aren’t life-threatening—think mild infections, minor injuries, or lingering symptoms that can’t wait for a regular appointment. These centers often have flexible hours and can address a wide spectrum of needs, from sprains and flu symptoms to minor cuts and burns.
Understanding emergency room visits in context
Emergency rooms, or ERs, are designed to handle critical or potentially life-threatening situations, such as chest pain, difficulty breathing, severe trauma, or sudden weakness on one side of the body. Explaining this distinction to Medicare clients ensures they understand that the ER is reserved for true emergencies, while urgent care is an appropriate alternative for less severe issues.
Why Discuss Cost Differences with Clients?
Potential impact on budget and planning
Healthcare costs can significantly impact the financial well-being of Medicare beneficiaries. By discussing the cost differences between urgent care and ER visits, you equip clients to better predict and manage their out-of-pocket expenses, including copays and deductibles. This information is especially crucial for those on fixed incomes or with limited resources.
Supporting informed healthcare choices
Clients often assume that every medical concern requires an ER visit. When you clarify the scenarios that call for urgent care versus emergency services, you help Medicare beneficiaries avoid unnecessary expenses and make empowered choices about their care—leading to greater satisfaction and reduced financial surprises.
How Do Costs Differ for Medicare Beneficiaries?
Cost-sharing basics: urgent care vs ER
For Medicare clients, cost-sharing arrangements can vary depending on their coverage. Generally, urgent care visits involve a lower copayment compared to emergency room services. Most Medicare Advantage and Original Medicare plans require beneficiaries to pay a set amount for urgent care, while ER visits tend to include higher copays or coinsurance, and sometimes an annual deductible applies.
Factors influencing out-of-pocket expenses
The total costs faced by Medicare beneficiaries depend on several factors: the chosen plan, if any deductibles or copays have been met, and whether the service is provided at an in-network facility or outside the network. Explaining these elements helps clients anticipate expenses and plan accordingly.
What Questions Do Clients Commonly Ask?
Clarifying coverage uncertainties
Clients often wonder, “Will Medicare cover my urgent care visit?” or “What if I go to the ER but it’s not an emergency?” Address these concerns by explaining that coverage is generally available for medically necessary services, but out-of-pocket expenses will differ. Emphasize it’s important to document why urgent care or ER was chosen in each example.
Addressing common Medicare misconceptions
Some myths persist, like “Medicare pays the same no matter where I go” or “Emergency room visits are always covered in full.” As a licensed insurance agent, correcting these misunderstandings is key. Use clear, plan-neutral language to ensure clients grasp the differences and avoid unwelcome billing surprises.
Effective Strategies for Client Education
Communicating compliance-friendly information
Stay plan-neutral and avoid recommending any specific plan feature or provider. Focus on what all Medicare beneficiaries should know: the basic coverage structure, definitions, and the importance of making care choices based on medical need, not just convenience. Use consistent language—refer to yourself as a “licensed insurance agent” and avoid implying any Medicare affiliation.
Utilizing plan-neutral educational materials
Choose or develop materials that highlight the contrasts between urgent care and ER costs without referencing carrier or product names. Infographics, cost-comparison charts using generic ranges, and real-life scenarios can help. Always include a disclaimer that coverage specifics depend on an individual’s Medicare plan and recommend reviewing an Evidence of Coverage document for exact details.
Scenario Example: Making the Right Choice
Walking clients through a sample scenario
Imagine a client wakes up with a painful, swollen wrist after a fall, but there are no open wounds or bone showing. Walking them through this scenario lets you discuss why urgent care—rather than the ER—could be more appropriate, both medically and financially, assuming no signs of severe trauma.
Highlighting decision-making criteria
Empower clients to ask themselves key questions: Are symptoms severe or life-threatening? Has there been confusion, chest pain, difficulty breathing, or uncontrollable bleeding? If yes, the ER is essential. For less severe concerns, urgent care could provide substantial savings and quicker access to care.
How Can Agents Stay Compliance-Focused?
Avoiding non-compliant communication pitfalls
Never promise that Medicare will “always” cover a specific cost, or imply clients are guaranteed to save by choosing urgent care over the ER. Avoid product names, carrier references, or suggesting one coverage is superior. When in doubt, refer back to official plan documents, or encourage clients to contact their plan provider for confirmation.
Reinforcing plan-neutral client guidance
Keep the focus on education. Remind clients that their costs are determined by the structure of their individual Medicare plan, and that their decision should always be guided by the severity of their symptoms, not just financial considerations. Your role is to help them confidently navigate options, not to recommend specific medical action.